- The Pulse Newsletter
- Posts
- The End of Cheap Money
The End of Cheap Money
Something Will Break, Private Funds in Court, Diesel Deal

Marc Beavis
October 12, 2026

It's Monday, October 12, 2026, and I’ll kick things off with a Happy Thanksgiving greeting for our Canadian readers. Hope everyone is having a great holiday.
As for this week's stories, I’ve selected a mix of topics. First off, the Globe and Mail asks whether Canadian investors, heavy on stocks and light on bonds, are ready for higher rates; I’ll look at that question. I’ll also look at the odd tension happening in the bond and equity markets. In the US, the Supreme Court weighed Intel's 401(k) case on private funds, and President Trump struck a deal for Russian diesel to ease near-record fuel prices.
One quick addition this week: In the Market Movers section below, you can now click on any stock ticker to visit its Blossom Social page, where you'll find company financials, earnings information, and insights from the investing community. It's a handy way to dig a little deeper into the stocks making headlines.

Market Recap: U.S. and Canada
The markets finished the week higher, but the path there was anything but even. US stocks climbed early, with the S&P 500 setting a fresh record on Tuesday. The TSX took a sharp hit on Wednesday as yields climbed worldwide and then spent most of the week in the red, and Thursday's tech selloff dragged the Nasdaq 100 below where it started the week. Brent crude pushed past US$104 a barrel, so that was also a factor this week. We saw a broad rally on Friday, pulling all four indices back into positive territory.
As for the numbers, the S&P 500 led with a 1.15% gain on the week, followed by the Dow Jones at 0.93%. The TSX added 0.53%, while the Nasdaq 100 trailed with a 0.24% gain.

Week ending October 9, 2026
Notable Stories This Week
PTC ($PTC) climbed 33% on Monday after Schneider Electric agreed to buy the Boston-based industrial software maker in an all-cash deal. The US$205-per-share offer values PTC's equity at about US$22.6 billion, a 42% premium to its prior close, with closing expected by the third quarter of 2027. Investors in Paris were far less enthusiastic, sending Schneider's own shares down nearly 10% on the day.
Aritzia ($ATZ) rose roughly 18% on Friday after second quarter revenue climbed 44% to $1.17 billion on a 35% jump in comparable sales. US revenue grew 60%, and the Vancouver retailer raised its full-year outlook to between $4.78 billion and $4.88 billion. Its adjusted EBITDA margin hit a second quarter record of 21%, excluding tariff refunds.
Humana ($HUM) gained 12% on Friday after the insurer emerged as the main beneficiary of newly released 2027 Medicare Advantage star ratings. Those ratings set quality bonus payments for 2028, and they mark a turnaround after two straight years of disappointing scores that weighed on the stock.
T-Mobile ($TMUS) fell 9.5% on Friday after SpaceX agreed to buy a nationwide portfolio of low-band 800 MHz spectrum from Grain Management, bringing Starlink a step closer to competing as a traditional wireless carrier. AT&T dropped 6.4% on the same news as investors weighed the risk of a price war in an already saturated US market. Financial terms weren't disclosed, and the deal still needs FCC approval.
Emera ($EMA) slipped in early trading Tuesday after announcing an all-stock deal to acquire Canadian Utilities for $14.3 billion, billed as the largest merger between two Canadian companies on record. The combined utility will carry an enterprise value of about $72 billion and plans a $32 billion capital program through 2030. ATCO, which controls Canadian Utilities, rose 12.8% in morning trading as it prepares to spin off a separate industrial services company.
Major Economic Stories | At a Glance
Canada Sheds 68,000 Jobs, Erasing the Year's Gains


Canada lost 68,300 jobs in September, a wide miss against expectations for a gain of about 9,000, while the unemployment rate edged up to 6.5% from 6.4%. The jobless rate stayed contained only because people left the labour force, with the participation rate falling to 64.8%, its lowest in 29 years outside the pandemic.
Sector losses: education and health care down 58,400 combined, with the public sector leading the decline
Youth employment: down 48,000, the hardest-hit age group for a second month
Wages: permanent employee pay up 2.3% year over year, from 2.0% in August
Year to date: net loss of 41,200 jobs, versus a gain of 211,300 at this point last year
US Consumer Mood Slides; Current Conditions Hit Record Low

The University of Michigan's preliminary sentiment index fell to 46.3 in October from 48.1, below the 47.6 consensus and the lowest reading since May. Of note, the current conditions gauge dropped 12.2% to 44.7, an all-time low, as high prices and borrowing costs sent views on buying big-ticket items sharply lower.
Expectations index: 47.3, up 2.2% from September
Year-ahead inflation expectations: 4.7%, up from 4.6% and rising for a second month
Year over year: sentiment down 13.6% from October 2025
Income split: lower-income consumers and those with smaller stock portfolios saw the steepest drops
TOP INSIGHTS
Canada's Job Market Is Shrinking From Both Ends
Fewer Canadians are working, and fewer are even looking for work. When you combine this with losses clustered in government-funded services, it points to a labour market that’s being reshaped by slower immigration, fewer international students and an ageing population. Then, we see tighter public budgets doing the rest. Trade disruption, the risk everyone had been bracing for, barely registered in this report.
All of this together shows up as a tougher path in for young people and newcomers, and fewer openings in sectors that have long been a reliable source of stable jobs. A shrinking labour force also caps how fast the economy can grow without stoking inflation, so that’s an uncomfortable mix for anyone hoping for both job security and lower prices.
I think the unemployment rate understates just how soft this market is, and I'd expect it to drift higher once participation stabilizes. Here's something I think we should watch for: whether the public sector cuts spread into private hiring over the next couple of reports. If they do, the case for any Bank of Canada tightening this year falls apart.
The Bank Of Canada Is Boxed In, And Markets Know It
Before Friday, traders were leaning toward a rate hike this month to deal with inflation running above target. Then, with one weak employment report, those odds were cut sharply. Two-year yields fell, and the loonie weakened. That tells you how fragile the hawkish case already was. The Bank is now staring at falling employment and stubborn prices at the same time.
That tension is going to hit borrowers directly and anyone renewing a mortgage in the next year is watching a central bank that wants to fight inflation but can't afford to push a softening job market over the edge. Then you add a weaker Canadian dollar adding its own pressure, and you’re in a tough spot.
The Bank will probably hold on October 28 and then will assess the September inflation print as it contemplates what to do in December. Unless that report comes in well above expectations, I don't see the Bank hiking into two straight months of job losses.
American Consumers Are Splitting Into Two Economies
I know I watch the Michigan survey closer than most, and I’m seeing a strange gap: people feel worse about today than at any point on record, and yet slightly better about the year ahead. It’s a bit tough squaring that circle. The sharpest declines came from lower-income households and those without much in the stock market, while anyone riding the equity rally is holding up better. That's a K-shaped pattern, and it's getting wider.
For families that are stretched by high prices and borrowing costs, big purchases are being pushed off, which will have an impact on retailers and automakers heading into the holidays. The rising inflation expectations also complicate the Fed's job after its September hike, since a public that expects higher prices tends to behave in ways that keep them high. Self-perpetuating, you could say.
I'm still leaning toward softer spending from the lower half of the income ladder showing up in the data by year-end, even if aggregate numbers hold up for now. I know I’ve been wrong on this for a few quarters now, but that’s my story and I’m sticking to it. Next week's retail sales report is the first real test of whether this mood is turning into an actual pullback.
The Week Ahead
US CPI lands Wednesday, with headline inflation expected to climb to 3.6% from 3.4% and core inflation forecast at 2.5% from 2.4%, the first full read on prices since the Fed's September hike. Energy is driving most of the headline pressure, and a hotter core number would reopen the debate about another hike, while an in-line print would let the Fed sit tight for now.
US retail sales follow on Thursday, with economists looking for a 0.3% gain after August's 1.2% jump, a key check on whether the gloom in this week's sentiment survey is translating into actual spending.
TOP STORY
Investors Are Still Positioned for Cheap Money

More than half of Canadian financial assets sit in equities
Bond funds hold just 13% of Canadian mutual fund assets
Households added $275 billion in stocks over the past year
US portfolio bond allocations are near 40-year lows
For four decades, falling interest rates have trained a generation of investors to lean on stocks and treat bonds as an afterthought. Or worse. The Globe and Mail is making the case that era is over, with inflation and a global scramble for capital now pushing yields higher. Defined-contribution pensions and group RRSPs have funnelled retirement savings into stock-heavy portfolios, and a TSX that's climbed 18% in the past year hasn't given anyone reason to rethink.
Bonds Deserve a Second Look
Now, after their worst year on record in 2022, bonds have picked up a reputation as dead money, but the recent selloff has left parts of the market offering real income and a valuation cushion they haven't had in years. BlackRock's Jean Boivin says that sticky inflation, heavy government borrowing and growing private investment needs leave little reason for yield pressure to fade.
Strong Earnings Are Hiding the Real Risk
If these higher yields do stick, investors might start souring on paying up for richly valued, long-duration stocks or companies that depend on cheap credit. US valuations have already been sliding for a year, but that trend has been masked by an extraordinary run of corporate profits.
Full story here.

With the US 10-year Treasury yield now above 5%, the trade-off between stocks and bonds looks very different than it did just a few years ago. For many Canadians, years of near-zero rates made the choice easy, and stock-heavy portfolios did the rest. I'm curious to learn where our community draws the line. Please vote on this week's question:
Would a 5% bond yield be enough to get you to move some money out of stocks? |
LAST WEEK’S POLL RESULTS
In last week's poll, I asked what concerns you most about AI's rapid progress. A clear majority, 62%, said losing control of the technology, while 32% pointed to cybersecurity threats and just 6% chose job losses and economic disruption, evidence that readers are more worried about what AI could do than what it might take away. Thanks to everyone who voted.

READER COMMENTS
Losing Control
“Nil. Let AI provide feedback!” — pnelega
Cyber Threats
“Well, AI is not progressing as quickly as Cyberdyne was able to do it in the late 20th century projections, so there's that, at least.” — mrrobpog
Jobs and the Economy
“They're all extremely concerning IMO, but the one I see posing the biggest ‘near-term’ risk is job losses and economic disruption, so that's what I decided to go with. When jobs are lost to AI, they're essentially lost for good. Will AI create new jobs? Quite possibly over time, but I envision a substantial interim period which could result in unemployment numbers society as a whole is prepared for. TBD how this all plays out, but I'm getting more concerned as AI has seemingly been given the ‘all-go’ signal with no true guardrails to speak of. Everyone ready for a swarm of black swans?!?!?” — callawayguy
FIXED INCOME
Rates Keep Climbing and No One Knows Why

Canada's 10-year government bond yield is up half a point this year
US, French and Japanese yields have risen twice as much
CPP holds only 12% of its portfolio in government bonds
FAO food price index is up nearly 6% in a year
John Rapley, a contributing columnist for the Globe and Mail, says he’s sensing an odd tension in markets: bond yields keep climbing while stocks keep rising, and none of the usual explanations fully account for it. Inflation expectations, nominal growth and oil prices have all been floated, yet yields have outrun each of them. What's clearer, though, is the pressure underneath, from heavy government deficits and AI hyperscaler borrowing to hedge funds replacing the patient buyers who once anchored the market. As I noted in the economic update above, consumers already feel the weight of higher borrowing costs.
Governments Are Feeling the Heat First
Meanwhile, over in France, attempts to calm bond investors with budget cuts have set off widespread protests, and Rapley warns Britain is one disappointing budget away from another ‘Liz Truss’ moment. In the US, the Treasury Secretary's boast that he was “the house” has not aged well as investors sell American debt.
Without an AI Payoff, Stocks Look Exposed
Rapley's view is that unless AI delivers a major productivity breakthrough, rates could keep rising until the stock market gives way. With US investment flat outside of AI, he thinks it may be time to prepare for a rainy season.
Full story here.
PENSIONS AND THE LAW
Supreme Court Leans Toward Intel in 401(k) Case

Justices heard Anderson v. Intel oral arguments on October 6
Case turns on whether underperformance claims require a benchmark
Labor Department proposed easing rules on alternatives this March
Nearly two-thirds of participants want private market access, per Voya
There was a major court hearing this week at the US Supreme Court, looking at how much evidence employees need before they can sue a plan sponsor over weak returns. A former Intel employee argued the company's retirement plans lagged badly enough to breach its fiduciary duty, but lower courts have ruled that poor performance alone isn't enough. Justices across the ideological spectrum seemed generally aligned, with Clarence Thomas warning that you can't compare apples and oranges.
A Win for Intel Could Open the Door
Legal observers read the justices' questions as a strong signal they'll side with Intel and affirm the Ninth Circuit. Ropes & Gray's Joshua Lichtenstein said a favourable ruling would give hesitant plan sponsors more confidence to add private funds with less fear of being sued.
Big Employers Will Still Move Slowly
Kent Mason, a partner at Davis & Harman, says he expects small and mid-size companies to move first, since the largest employers face the most litigation risk even under new Labor Department rules. Momentum is building anyway, with Constitution Capital's new collective investment trust already lining up more than US$1 billion in plan assets and commitments.
Full story here.
SANCTIONS AND GLOBAL ENERGY
Trump Turns to Russia to Ease Diesel Prices

Russia will supply over 300,000 metric tons of diesel immediately
US Treasury license allows Russian diesel imports until April 7, 2027
US diesel averaged a near-record $6.28 a gallon Thursday
Diesel prices are up 70% since the Iran war began
After a seemingly friendly call with Vladimir Putin this week, President Trump temporarily lifted sanctions on Russian fuel that were designed to starve Moscow of war revenue. The timing is significant, with diesel costs weighing on farmers, truckers and home heating bills less than a month before the November 3 midterms. Trump says more supply will follow in November and beyond, depending on the state of Russian refineries that Ukrainian strikes have damaged. Diesel futures fell almost 5% on the news.
Ukraine and Republicans Push Back
Ukrainian President Volodymyr Zelenskiy called it a weak decision by strong partners, warning that Russia will repay the diesel with further terror. Republican Representative Don Bacon argued the moment calls for tougher sanctions on Putin's war machine instead.
Expect Little Relief at the Pump
Analysts doubt the volumes are large enough to move prices for long, with Rory Johnston calling the deal a “nothing burger.” The White House is also preparing to lean on the Defense Production Act to expand refining output, though refining executives say a brand-new refinery would take years to build.
Full story here.
Stelco says it is proceeding with Ontario layoffs after Ottawa issues ultimatum

Company says in letter it is not violating Investment Canada Act commitments
The best workplaces make it easy for employees to say no

Workplaces that make it easier for employees to say no to excessive workloads are more likely to see strong performance and innovation, new research from O.C. Tanner suggests
Healey faces £35bn Budget challenge to meet spending pledges, says think tank

The Institute for Fiscal Studies says the government will need a "top-up" of billions of pounds if it wants to meet its spending plans.
How to avoid getting stung if you miss credit card payments

People are increasingly falling behind on credit card repayments, so here's the best way to get debt advice.
UAW tries to reassert political power in Michigan despite internal divisions
Membership is divided over which party best represents working-class interests.
Trump sticks with tariffs even as US voters turn against them before the midterms
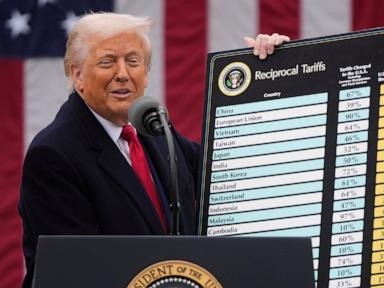
President Donald Trump shows no signs of budging from a trade policy that many Americans don't like as the midterm elections loom

NEW FEATURE!
Click any stock ticker to explore its page on Blossom Social. Review key financial data, learn more about the company, explore earnings information, and see what other investors in the community are saying.
Top 10 Weekly Gainers
US and Canadian stocks over $10B market cap, 5-day price change as of October 12, 2026. Prices shown in the currency of the listed exchange (CAD for TSX; USD for NYSE and Nasdaq)
Ticker | Company | Exchange | Price | 5-Day Change |
Crown Castle Inc. | NYSE | $81.01 | +19.9% | |
Aritzia Inc. | TSX | $146.91 | +17.8% | |
Snap Inc. | NYSE | $6.53 | +16.4% | |
XP Inc. | NasdaqGS | $32.60 | +15.8% | |
Bending Spoons S.p.A. | NasdaqGS | $37.04 | +15.3% | |
Talen Energy Corporation | NasdaqGS | $379.77 | +14.4% | |
SBA Communications Corporation | NasdaqGS | $184.28 | +13.9% | |
American Tower Corporation | NYSE | $182.56 | +12.5% | |
Shopify Inc. | NasdaqGS | $179.22 | +11.9% | |
Zscaler Inc. | NasdaqGS | $225.78 | +11.9% |
Top 10 Weekly Losers
Ticker | Company | Exchange | Price | 5-Day Change |
Cerebras Systems Inc. | NasdaqGS | $146.62 | -19.2% | |
Tempus AI Inc. | NasdaqGS | $67.99 | -18.6% | |
TTM Technologies Inc. | NasdaqGS | $110.33 | -17.1% | |
Onto Innovation Inc. | NYSE | $273.74 | -15.9% | |
Arm Holdings plc | NasdaqGS | $255.24 | -15.7% | |
IonQ Inc. | NYSE | $36.27 | -15.6% | |
Vicor Corporation | NasdaqGS | $259.40 | -15.1% | |
Seagate Technology Holdings plc | NasdaqGS | $753.25 | -15.1% | |
IREN Limited | NasdaqGS | $34.80 | -14.0% | |
Coherent Corp. | NYSE | $288.02 | -13.7% |
Most Overbought
US and Canadian stocks, Relative Strength Index as of October 12, 2026
Ticker | Company | Exchange | Sector | RSI |
XP Inc. | NasdaqGS | Financials | 90.8 | |
Everpure Inc. | NYSE | Information Technology | 81.5 | |
PTC Inc. | NasdaqGS | Information Technology | 81.0 | |
Dynatrace Inc. | NYSE | Information Technology | 78.4 | |
Frontline plc | NYSE | Energy | 77.6 | |
On Holding AG | NYSE | Consumer Discretionary | 77.6 | |
Shopify Inc. | NasdaqGS | Information Technology | 76.9 | |
Palantir Technologies Inc. | NasdaqGS | Information Technology | 76.2 | |
HF Sinclair Corporation | NYSE | Energy | 76.0 | |
GitLab Inc. | NasdaqGS | Information Technology | 75.4 |
Most Oversold
Ticker | Company | Exchange | Sector | RSI |
MGM Resorts International | NYSE | Consumer Discretionary | 13.5 | |
BCE Inc. | TSX | Communication Services | 18.6 | |
U-Haul Holding Company | NYSE | Industrials | 21.1 | |
Annaly Capital Management Inc. | NYSE | Real Estate | 22.0 | |
Las Vegas Sands Corp. | NYSE | Consumer Discretionary | 23.2 | |
AGNC Investment Corp. | NasdaqGS | Real Estate | 24.7 | |
Comcast Corporation | NasdaqGS | Communication Services | 24.9 | |
Praxis Precision Medicines Inc. | NasdaqGS | Health Care | 25.1 | |
Wynn Resorts Limited | NasdaqGS | Consumer Discretionary | 25.2 | |
Madrigal Pharmaceuticals Inc. | NasdaqGS | Health Care | 25.3 |
The Relative Strength Index (RSI) can provide a signal that suggests a stock is either overbought or oversold.
📈A stock that has an RSI over 70 is considered to be in “overbought” territory. This might suggest that the stock is due for a pullback, however it is not a recommendation to sell.
📉A stock that is trading with an RSI below 30 is considered to be in “oversold” territory. This might suggest that the stock is due for a recovery, however it is not a recommendation to buy. Always perform your own due diligence.
Reply