

It's Sunday, October 25, 2026, and welcome to this week’s Pulse. In an interesting privacy rights issue, Google is pressing Senators to rework Bill C-22, Ottawa's lawful-access legislation, before it creates what the company calls a new surveillance infrastructure. In the US, President Trump is lifting tariffs on some Canadian farm and forestry goods days before Maine's Senate vote, consumer sentiment is hovering near a record low, and the Dallas Cowboys Cheerleaders have just formed a union. Enjoy today’s read, and yes, pompoms are optional.

Market Recap: U.S. and Canada
Two clearly distinctive halves played out in North American markets this week. From Monday through Wednesday, stocks climbed steadily, with the Nasdaq 100 out in front as tech names rallied into the heart of earnings season. That momentum broke on Thursday, when results from Meta and Tesla reignited worries about how much the biggest companies are spending on AI, and that sent chip stocks sharply lower as oil climbed to its highest level since May. Canadian stocks were hit particularly hard that day as gold and copper slid and miners sold off. Friday was a bit calmer, but didn’t bring a ton of relief. The Dow gave back a big chunk of its weekly gain as Brent crude settled at a six-month high.
As for the numbers, the Dow Jones was the only major index to finish higher, gaining 0.41% on the week. The S&P 500 slipped 0.47%, the Nasdaq 100 fell 0.79%, and the TSX brought up the rear with a 1.07% decline.
Note: We Have a Winner! Thank you to everyone who weighed in on last week’s chart survey. We did have a number requesting the 4-part chart, but the overwhelming majority voted for a more traditional look (84%), so we’ll be running with the chart you see here. Personally, I like it.

Notable Stories This Week
Meta Platforms ($META) fell 9.4% this week even though third quarter revenue rose 26% to $64.6 billion, comfortably ahead of expectations. Investors focused on the cost side instead: free cash flow turned negative at about $2.1 billion for the quarter, the company lifted the low end of its 2026 capital spending range to $135 billion to $145 billion, and a settlement with state attorneys general added a $9.9 billion charge. Meta also announced a new class of non-voting shares that works like a two-for-one split, starting in January.
Hasbro ($HAS) gained 18.9% after Tuesday's third quarter results came in well ahead of expectations, with adjusted earnings of $2.90 a share against a consensus of $1.85. Magic: The Gathering topped $600 million in quarterly revenue for the first time, up 34%, and the company raised its 2026 revenue growth outlook to 7% to 9% in constant currency while doubling its buyback target. About $55 million in tariff refunds helped, but adjusted operating profit still grew by more than a third without them.
Celestica ($CLS) dropped 15.1% this week, including a slide of roughly 12% on Thursday, as the selloff in AI infrastructure stocks hit one of the TSX's biggest AI hardware names. The move came before the company has even reported, with third quarter results and an investor day both scheduled for early next week and analysts expecting earnings of $2.94 a share on $5.37 billion in revenue.
Waste Connections ($WCN) rose 11.1% after Wednesday's third quarter results beat expectations and the company raised its full-year outlook for the second time this year. Revenue climbed 7.3% to $2.64 billion, adjusted earnings came in at $1.58 a share against $1.44 a year ago, and solid waste core pricing held at 5.5%. The company also raised its quarterly dividend by 10%.
SpaceX ($SPCX) finished the week up just 1%, but it was a busy one for the newly public company. Tuesday's third quarter results showed its first profit as a public company, net income of $4.4 billion on revenue of $14.6 billion, up 161%, with revenue from its AI segment nearly tripling to $7.56 billion and overtaking Starlink. The shares jumped on Wednesday, then gave back more than half of that gain on Thursday as the broader AI selloff took hold.
Major Economic Stories | At a Glance
Gasoline Pushes Canadian Inflation Higher While Core Measures Cool


Canada's inflation rate edged up to 3.1% in September from 3.0% in August, a touch below the 3.2% economists expected. Gasoline did almost all of the work, up 27.8% from a year ago, while the CPIX measure of core inflation eased to 2.2% from 2.4%.
CPI-trim and CPI-median: 1.8% and 1.9%, both down a tenth from August
Groceries: 1.7% year over year, the slowest pace since May 2024
Shelter: 1.8%, up from 1.5% on home insurance, maintenance and repair costs
CPI excluding gasoline: 2.2%, down from 2.4% in August
US Consumer Sentiment Holds Near Its Lowest Levels on Record

The University of Michigan's consumer sentiment index finished October at 48.0, revised up from a preliminary 46.3 but still just below September's 48.1 and the second-lowest final reading in the survey's 74-year history. Year-ahead inflation expectations climbed to 4.7% from 4.6%, and buying conditions for durable goods dropped 18% as high prices and borrowing costs kept big-ticket purchases on hold.
Current conditions index: 46.7, down from 50.9 in September
Expectations index: 48.8, up from 46.3 in September
Long-run inflation expectations: 3.5%, up from 3.4% and above the 2024 range of 2.8% to 3.2%
Versus prior periods: about 10% below October 2025 and 15% below February, before the Iran war began
TOP INSIGHTS
Canada's Inflation Rise Is A Gasoline Story
If we ignore what's happening at the pump for just a moment (bear with me), Canada's inflation picture looks remarkably calm. CPI-trim, one of the Bank of Canada's two preferred core gauges, has now held below 2% for four straight months, and the grocery relief seems to be real. The spillover from energy, though, shows up in places like airfares, which jumped more than 19% from a year ago.
For households, this is the most frustrating kind of inflation, because it hits the costs people notice every day. Filling the tank and booking a flight home for the holidays feel far more expensive, even though the weekly grocery bill might finally feel a tad more acceptable. For the Bank of Canada, it sustains that awkward choice: raising rates won't lower the price of oil, but it will make mortgages and lines of credit more expensive for families.
That said, I’m going with the majority and expect the Bank to raise rates this coming week anyway. Governor Tiff Macklem has warned that the risk of inflation broadening and becoming more persistent has gone up, and with markets pricing a hike, if it just stands still, it would look like the Bank ignoring its own warning. Where I'd push back is on the idea of a long series of hikes. In the event we do see an easing in oil prices, the core trend we just looked at gives the Bank every reason to stop at one, and that's the outcome I'm leaning toward.
Americans Are Starting To Treat Higher Inflation As Permanent
The Michigan headline sentiment number gets all the attention, but the inflation expectations underneath it are the more important signal. Year-ahead expectations sat at 3.4% in February, before the Iran war began, and both the short- and long-run measures have moved higher since, with long-run expectations now above anything we saw in 2024. When people tell us they expect higher prices five years out, they're really saying that the oil shock doesn’t feel like a temporary thing anymore.
And, that shift changes behaviour. If they can muster the courage, workers will push harder for raises, businesses will feel more comfortable passing on costs, and households will pull purchases forward before prices rise again. All of these can keep inflation elevated long after gasoline eventually settles down. It's also part of why bond investors are demanding more to hold long-term Treasuries.
I’ll be watching to see whether the Fed's statement next week places a focus on this risk. I expect a hold, but I also think the language will make clear that a December hike is very much alive.
Big-Ticket Purchases Are Where The Consumer Squeeze Shows Up First
Most of the damage in October's sentiment survey came from one place: how people feel about buying cars, appliances and other durable goods. Big stuff, you might say. Interestingly, expectations about the economy actually improved a bit this month, and the drop in current conditions came almost entirely from that collapse in buying conditions. That's very focused pessimism, and it’s tied directly to financing costs.
Think about what that means at the dealership or the furniture store. We’ve got borrowing costs near multi-year highs and prices still climbing, so a new car or a kitchen renovation goes from a planned purchase to something families push into next year. Automakers, home furnishing retailers and appliance makers (again, the ‘big stuff’ suppliers) feel that first, and their weakness tends to ripple down to suppliers and manufacturing jobs.
I think this is an early warning sign that deserves some attention. Spending has held up so far, but if business orders and the holiday season both come in soft, it'll confirm that higher rates are finally biting where they usually bite first.
The Week Ahead
Durable Goods Orders for September, due Tuesday, are expected to rise about 3.5% after a 0.1% dip in August, with orders excluding transportation seen up 1.0%, a useful read on whether businesses are still investing as borrowing costs climb.
The Bank of Canada Interest Rate Decision on Wednesday is the big one, with markets putting roughly three-in-four odds on a quarter-point hike to 2.50%, which would be the Bank's first move in a year and its first increase since 2023. The updated Monetary Policy Report arrives alongside it, and its revised inflation forecasts will tell us whether the Bank sees one hike or the start of a cycle.
The Fed Interest Rate Decision, also on Wednesday, is expected to hold rates at 3.75% to 4.00% after September's hike, with odds of a move near 5%, so the focus will be on any dissents in favour of higher rates.
The Core PCE Price Index for September, due Thursday, is forecast to tick up to 3.1% from 3.0%, and a hotter print would strengthen the case for a December hike.
Personal Income and Personal Spending, also Thursday, should show spending rising about 0.3% after August's 0.9% jump, with income growth having slowed to 0.2% in August, a test of how long households can keep spending ahead of their paycheques.
IN PARTNERSHIP WITH HARVEST ETFS
Why Global Utilities Deserve a Closer Look | HUTL & HUTE

Electricity, water, telecommunications, and natural gas are essential to modern life, supporting the dependable demand and established cash flows that have long attracted investors to utilities.
Today, the utilities sector is evolving. Aging infrastructure, rising electricity demand from artificial intelligence (AI) and data centres, and the global energy transition are driving significant investment in power generation, transmission networks, and grid modernization.
For Canadian investors, global diversification offers access to utilities operating across different markets, broadening exposure beyond domestic businesses while helping reduce regional concentration risk. However, utilities remain sensitive to interest rates, regulation, currency movements and market conditions.
The Harvest Utilities Leaders Income ETF (TSX: HUTL)1 provides exposure to an equally weighted portfolio of 30 global utilities companies spanning electricity, telecommunications, and energy infrastructure. An active covered call strategy aims to generate monthly income.
The Harvest Utilities Leaders Enhanced Income ETF (TSX: HUTE)2 invests in HUTL and uses approximately 25% leverage to seek higher monthly income and growth potential, with additional investment risk.
1 Formerly Harvest Equal Weight Global Utilities Income ETF
2 Formerly Harvest Equal Weight Global Utilities Enhanced Income ETF
*See Harvest ETFs Disclaimer at the end of the newsletter
TOP STORY
Google Takes Its C-22 Fight to the Senate

Google urges Senators to amend lawful-access Bill C-22
Ministers could secretly order tech firms to change systems
Firms could be forced to keep customer metadata six months
Signal has threatened to leave Canada over privacy demands
Ottawa wants to give police and CSIS new tools for monitoring electronic communications, and some of the world's biggest tech companies are pushing back hard. Google's latest move is a briefing note to Senators warning that the bill could create what it calls a "new surveillance infrastructure." It wants stronger encryption protections and limits on secret ministerial orders, while the government insists independent oversight keeps the bill accountable.
Secrecy Is the Sticking Point
Google says secret surveillance directives leave Canadians unable to scrutinize state power, and that blanket metadata retention would create tempting targets for hackers. Public Safety Minister Gary Anandasangaree's office pushes back and says that disclosure would hand criminals a roadmap, and that orders need Intelligence Commissioner approval.
The Senate Is Now the Last Real Check
The bill could reach a Senate committee as early as next week, where amendments are expected. If Senators don't tighten the encryption language, Canada risks losing privacy-focused services, and one Toronto-based VPN provider is already planning to leave.
Full story here.

Bill C-22 forces a trade-off: how much privacy are we willing to give up so police can keep pace with crime that increasingly happens online? The government says oversight protects us, while Google and others argue secrecy undermines it. I'm curious to learn where our community lands on this controversial topic, so please vote on this week's question:
Which matters more to you in this debate?
LAST WEEK’S POLL RESULTS
In last week's poll, I asked how you're responding to the current mix of record stock prices and bond market caution. Half of you said you're staying the course, while 27% are adding more defensive holdings and 23% are taking some profits, a fairly measured response given how far stocks have run. Thanks to everyone who voted.

READER COMMENTS
Holding Steady
“I am careful, but will buy if price and return work for me, mainly ETF funds that pay good distributions, no single stock purchases for a while.” — mcdoug
Getting More Defensive
“I'll keep my response short and simple for a change. My recent activity has primarily been a mix of 'taking profits' and 'adding more defensive holdings.' I'd admittedly be taking more profits than I already am if I didn't have to consider tax implications.” — callawayguy
Locking In Gains
“Think there will be a correction.” — palazzi_evaders
TRADE
Trump Trims Canadian Tariffs Ahead of Maine Vote

Trump lifts 50% tariffs on some Canadian farm, forestry goods
Exemptions cover plywood, paper, packing crates and seaweed
Relief starts October 30, four days before the midterms
Canoes, paints and chest freezers join the tariff list
The trade fight between Canada and the US got a small, carefully timed adjustment this week. President Trump signed an order removing tariffs on Canadian products that Maine businesses depend on, after Republican Senator Susan Collins pressed for help in a tight reelection race. The White House offset the relief by adding a new batch of Canadian goods to the list, and Collins says the change will help Maine's blueberry, potato, apple and seaweed producers.
Border States Feel This Fight First
Maine and Michigan are deeply tied to Canada's economy, and Republicans may need both Senate seats to keep their majority. Trump also dropped his threat to block Bombardier from the US market after pressure from Kansas lawmakers, an obvious sign that local pain is playing a big role in shaping trade policy.
Don't Mistake Carve-Outs for a Deal
Trump says Canada is working on a deal, but the standoff that began in August, and Canada's retaliatory tariffs, are still in place. For Canadian exporters, election-timed carve-outs make planning harder, and I'd expect more of them until real negotiations resume.
Full story here.
US CONSUMER
American Consumers Are Running Out of Optimism

October sentiment is the second-lowest final reading in 74 years
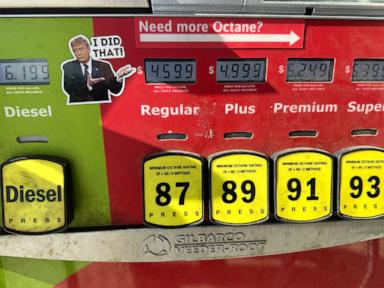
US gas averages $4.29, up about 43% since February
Inflation ran 3.7% in September, well above the Fed's target
Employers added just 29,000 jobs in September, missing forecasts
As I covered in the economic update above, American households feel worse about the economy than at almost any point in the survey's history, just weeks before the midterms. High gasoline prices and stubborn inflation are doing most of the damage, with oil hitting a six-month high on Friday. Sentiment improved among Democrats and Republicans, but a drop among independents more than offset those gains, an ominous detail considering affordability is a top voter concern.
The Economy Looks Better on Paper Than at the Kitchen Table
Consumer spending jumped 0.9% in August and GDP kept growing through the spring, so the hard data hasn't cracked. But rising long-term Treasury yields are pushing up mortgage and credit card rates, which adds a second squeeze on top of higher prices.
Watch Whether Gloom Turns Into Spending Cuts
Hiring slowed sharply in September, and shoppers expect inflation to climb further. That’s a combination that eventually turns even the most optimistic consumer into a stingier one. Let’s see what happens with holiday spending, where we’ll see a clash between holiday sentiment and the harsh reality of the cost-of-living challenges so many are facing.
Full story here.
SPORTS BUSINESS
Dallas Cowboys Cheerleaders Form a Historic Union

Cowboys formally recognized the cheerleaders' new union Friday
Likely the first pro cheer union since the 1990s
The 36-member squad's union now heads into bargaining
Netflix fame helped deliver a 400% raise in 2025
Ok, so this isn’t a story that’s going to affect most of our wallets directly, but I couldn’t resist the report. One of the most recognizable brands in American sports just picked up a new label: unionized. The Dallas Cowboys team has formally recognized the cheerleading squad’s bargaining unit after what both sides called constructive talks, skipping the usual organizing fight. The Netflix series America's Sweethearts has given the squad more leverage than ever, a long way from the 1990s, when cheerleaders earned as little as $15 a game.
Visibility Turned Into Bargaining Power
Some of the veteran dancers on the squad were already slated to earn more than $75 an hour after the 2025 raise, and an earlier minimum-wage lawsuit ended in a settlement. A formal contract would lock in those gains instead of leaving them to the team's goodwill.
Other NFL Squads Will Be Watching Closely
At this point, it's unclear how many members will be represented, and contract talks will test how far the team will go. If Dallas sets a strong template, I think we can expect cheer squads across the league to ask why they don't have the same protections.
Full story here.


Hundreds of thousands protest again in France over school funding, living costs

Italy deploys hundreds of soldiers as protests planned across Europe

White House lifts tariffs on some Canadian goods as midterm elections loom

Zuckerberg wins Meta deal to help him foot bill for possible California billionaire tax
Inflation, earnings reports and the mood of consumers and the Federal Reserve fill out a busy week
Halloween candy sales are off to a slow start amid high chocolate prices and affordability concerns

Click any stock ticker to explore its page on Blossom Social. Review key financial data, learn more about the company, explore earnings information, and see what other investors in the community are saying.
Top 10 Weekly Gainers
US and Canadian stocks over $10B market cap, 5-day price change as of October 23, 2026. Prices shown in the currency of the listed exchange (CAD for TSX; USD for NYSE and Nasdaq)
Ticker | Company | Exchange | Price | 5-Day Change |
Zscaler Inc. | NasdaqGS | $255.15 | +23.0% | |
JFrog Ltd. | NasdaqGS | $100.62 | +19.4% | |
Hasbro Inc. | NasdaqGS | $117.44 | +18.9% | |
HubSpot Inc. | NYSE | $270.88 | +17.3% | |
SailPoint Inc. | NasdaqGS | $21.79 | +16.2% | |
Check Point Software Technologies Ltd. | NasdaqGS | $159.03 | +15.3% | |
Charles River Laboratories International Inc. | NYSE | $345.37 | +15.1% | |
Figma Inc. | NYSE | $24.64 | +14.7% | |
Rubrik Inc. | NYSE | $128.74 | +14.5% | |
Roper Technologies Inc. | NasdaqGS | $438.14 | +14.5% |
Top 10 Weekly Losers
Ticker | Company | Exchange | Price | 5-Day Change |
Carpenter Technology Corporation | NYSE | $284.66 | -24.5% | |
Sea Limited | NYSE | $74.63 | -20.4% | |
Comfort Systems USA Inc. | NYSE | $1,160.86 | -19.3% | |
Graco Inc. | NYSE | $66.99 | -18.3% | |
Sterling Infrastructure Inc. | NasdaqGS | $355.30 | -16.3% | |
Howmet Aerospace Inc. | NYSE | $185.91 | -15.9% | |
ATI Inc. | NYSE | $156.88 | -15.5% | |
Flex Ltd. | NasdaqGS | $76.55 | -15.4% | |
Celestica Inc. | TSX | $364.40 | -15.1% | |
TTM Technologies Inc. | NasdaqGS | $80.11 | -14.7% |
Most Overbought
US and Canadian stocks, Relative Strength Index as of October 23, 2026
Ticker | Company | Exchange | Sector | RSI |
Hasbro Inc. | NasdaqGS | Consumer Discretionary | 87.5 | |
Tradeweb Markets Inc. | NasdaqGS | Financials | 82.0 | |
Arcosa Inc. | NYSE | Industrials | 82.0 | |
Paycom Software Inc. | NYSE | Industrials | 81.9 | |
Paylocity Holding Corporation | NasdaqGS | Industrials | 81.7 | |
Waste Connections Inc. | NYSE | Industrials | 80.9 | |
Roper Technologies Inc. | NasdaqGS | Information Technology | 80.4 | |
International Flavors & Fragrances Inc. | NYSE | Materials | 80.0 | |
Allegion plc | NYSE | Industrials | 79.8 | |
Cintas Corporation | NasdaqGS | Industrials | 78.4 |
Most Oversold
Ticker | Company | Exchange | Sector | RSI |
Carpenter Technology Corporation | NYSE | Industrials | 11.1 | |
Sea Limited | NYSE | Consumer Discretionary | 18.1 | |
Curtiss-Wright Corporation | NYSE | Industrials | 19.0 | |
Howmet Aerospace Inc. | NYSE | Industrials | 19.5 | |
FirstCash Holdings Inc. | NasdaqGS | Financials | 19.7 | |
Rivian Automotive Inc. | NasdaqGS | Consumer Discretionary | 20.9 | |
Comfort Systems USA Inc. | NYSE | Industrials | 21.1 | |
Flex Ltd. | NasdaqGS | Information Technology | 22.3 | |
MasTec Inc. | NYSE | Industrials | 22.7 | |
KLA Corporation | NasdaqGS | Information Technology | 23.3 |
The Relative Strength Index (RSI) can provide a signal that suggests a stock is either overbought or oversold.
📈A stock that has an RSI over 70 is considered to be in “overbought” territory. This might suggest that the stock is due for a pullback, however it is not a recommendation to sell.
📉A stock that is trading with an RSI below 30 is considered to be in “oversold” territory. This might suggest that the stock is due for a recovery, however it is not a recommendation to buy. Always perform your own due diligence.
*Harvest ETFs Disclaimer
Commissions, management fees and expenses all may be associated with investing in Harvest Exchange Traded Funds, managed by Harvest Portfolios Group Inc. Please read the relevant prospectus before investing. The funds are not guaranteed, their values change frequently, and past performance may not be repeated.
Distributions are not guaranteed and may include a return of capital. Covered call strategies can limit potential gains on the portion of the portfolio subject to written calls and do not eliminate the risk of loss. This article is for informational purposes only and should not be considered investment, tax or financial advice. Investors should consult a qualified professional when making investment decisions.
The indicated rates of return are the historical annual compounded total returns (except for figures of one year or less, which are simple total returns) including changes in unit value and reinvestment of all distributions and do not take into account sales, redemption, distribution or optional charges or income taxes payable by any securityholder that would have reduced returns.
Certain statements in this communication constitute forward-looking statements (“FLS”). These statements are not historical facts but reflect the current expectations of Harvest, the Fund’s manager, regarding future results or events, and are subject to risks and uncertainties that could cause actual results to differ materially. Although Harvest believes the underlying assumptions are reasonable, FLS are not guarantees of future performance, and undue reliance should not be placed on them. Harvest undertakes no obligation to update or revise any FLS, except as required by law.
